
Last Updated on August 23, 2026 by Abdul Rehman
An accident can leave you managing injuries, vehicle damage, insurance calls, bills, and paperwork at the same time. A clear process helps you protect useful evidence and keep your claim organized.
Short answer: If you need accident claim help, protect your health and the evidence first. Report the incident, exchange information, photograph the scene, promptly notify the insurer, and keep all bills and messages. Before accepting a final settlement, compare it with your documented losses and seek legal advice if injuries, fault, coverage, or deadlines are disputed.
| Claim stage | What to do |
|---|---|
| At the scene | Get medical help, report the incident, and collect basic evidence |
| First notification | Tell the appropriate insurer promptly and obtain a claim number |
| Evidence | Save photos, reports, witness details, medical records, and repair documents |
| Financial records | Track medical costs, repairs, lost work, and other accident-related expenses |
| Adjuster contact | Keep notes of conversations, requests, dates, and documents provided |
| Settlement review | Check what the offer covers before agreeing to resolve the claim |
| Dispute | Request reasons in writing and follow the insurer’s review or appeal procedure |
| Legal questions | Check local deadlines and consider legal advice when the stakes are significant |
Table of Contents
Accident Claim Help: 8 Steps From the Scene to a Settlement
1. Protect your safety and get medical attention
Deal with immediate safety before paperwork. For vehicle crashes, the National Association of Insurance Commissioners advises calling emergency services when someone is injured and moving a drivable vehicle out of traffic when it can be done safely.
Medical records can also become important evidence when an injury forms part of the claim. Don’t delay necessary care because you’re worried about the insurance process.
2. Report the accident
Report a road crash to the police when local rules or the circumstances require it. At a business, workplace, or other property, notify the appropriate owner, manager, or employer.
Ask how to obtain any incident or police report. An official report can help establish basic details such as the time, place, people involved, and reported circumstances.
3. Collect evidence before it disappears
Photograph vehicle damage, the wider scene, road conditions, signs, hazards, and other relevant details. Get names and contact information for witnesses when possible.
After a vehicle collision, useful details include the other driver’s insurance information, license plate, vehicle details, accident location, and the attending officer’s information. NAIC specifically recommends collecting these details at the scene.
In the event of a fall or another property accident, photographs of the hazard, witness details, medical records, and maintenance information may be relevant. Readesh has a separate guide on premises liability claims for injuries caused by unsafe property conditions.
4. Notify the insurer promptly
Contact the appropriate insurance company and open the claim. Your policy may contain reporting requirements, so check its instructions rather than assuming every insurer follows the same timetable.
For auto claims, NAIC recommends contacting the insurer as soon as possible. The company will normally assign an adjuster to investigate the loss and assess what the policy may pay. Ask for the claim number, the adjuster’s contact information, and a list of required documents.
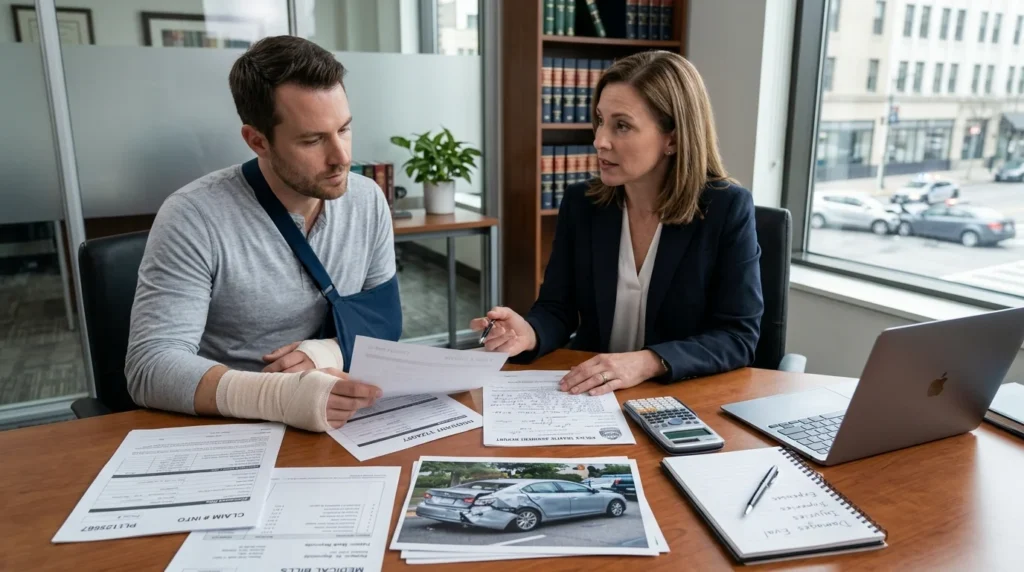
5. Build one claim file
Keep the paperwork together instead of searching through texts, emails, and folders later.
Your file may include:
- photographs and video;
- police or incident reports;
- witness information;
- medical records and bills;
- repair estimates and invoices;
- proof of missed work or lost income;
- transportation or other related receipts;
- insurer letters, emails, and forms;
- a dated record of calls with adjusters or agents.
NAIC recommends keeping notes and dates for conversations with insurance representatives. Evidence such as photographs, witness names, and detailed accident information may also be requested during the investigation.
For a broader explanation of injury evidence and the claims process, Readesh’s personal injury claims guide covers documentation, insurance involvement, and common next steps.
6. Document the losses you are claiming
Don’t focus only on the most visible bill. Depending on the circumstances of the accident, applicable law, liability, and available coverage, a claim can involve vehicle or property damage, medical expenses, lost wages, and other accident-related losses.
Keep proof for each amount. A spreadsheet or simple claim log can record the date, expense, amount, supporting document, and whether it has been submitted.
An injury claim may involve issues beyond easily calculated bills. Those issues depend heavily on local law and the facts, so avoid relying on generic online settlement calculators.
7. Review a settlement before accepting it
Compare any offer with your records. Check which property damage, treatment costs, lost income, or other items the insurer included. Ask questions when something is missing. NAIC advises consumers not to feel rushed into accepting a settlement and to request written explanations for claim decisions.
A final settlement can have legal consequences. If injuries are continuing, liability is disputed, or you don’t understand a release, consider getting advice from a qualified lawyer in your jurisdiction before signing it.
8. Escalate unresolved problems
If a claim is denied or valued below what your evidence supports, request the insurer’s reasoning in writing. Review the policy’s complaint, reconsideration, appraisal, or appeal provisions.
In the United States, consumers can contact their state Department of Insurance about problems with an insurer. Every state, the District of Columbia, and five U.S. territories have insurance departments that assist consumers.
An insurance dispute may also justify legal advice, particularly when serious injuries, substantial losses, disputed responsibility, or approaching legal deadlines are involved.
What You’ll Need to Manage the Claim
You don’t need special software. A digital folder plus a basic timeline can prevent important information from becoming scattered. Create separate folders for the accident report, photographs, medical documents, expenses, property damage, employment records, and insurer correspondence.
Rename files with dates so you can find them quickly. Keep copies of anything you send. Record when each item was submitted and whether the insurer acknowledged receiving it.
How Long Can an Accident Claim Take?
There isn’t one reliable timeline for every claim. A straightforward property-damage matter can differ greatly from a claim involving ongoing treatment, contested liability, several insurers, or litigation.
Legal deadlines also vary by jurisdiction and claim type. FindLaw notes that statutes of limitations vary by location and by the type of legal action. That distinction matters. An insurer’s internal reporting deadline and the legal deadline for filing a lawsuit are not necessarily the same. Check your policy and the law where the accident occurred.
When Should You Consider a Lawyer?
Legal advice becomes more useful as the financial or legal stakes rise. Consider speaking with a local lawyer when injuries are serious, treatment is continuing, fault is disputed, coverage is unclear, or an insurer denies the claim. You may also want advice before signing a broad release or when you’re unsure which limitation period applies.
Readesh’s guide on consulting a personal injury lawyer after an accident explains the lawyer’s role in evidence collection, claim preparation, negotiations, and litigation.
For U.S. readers concerned about cost, USAGov lists programs that may provide free or low-cost civil legal help, including assistance with personal injury and property damage matters.
Frequently Asked Questions
Start with your insurer for policy and claim procedures. For unresolved insurance issues in the United States, your state Department of Insurance can provide consumer assistance. Serious injuries, disputed liability, or legal deadlines may justify advice from a licensed local attorney.
Useful records can include photographs, driver and insurance details, witness contact information, police report details, medical documentation, repair records, and notes on insurer communications.
Ask for the reason and the applicable policy provision in writing. Review the insurer’s appeal or review procedure and provide missing evidence when appropriate. U.S. consumers can also seek assistance from their state insurance regulator.
You don’t have to accept an offer simply because it has been made. Compare it with your documented losses and ask questions about missing items. NAIC advises consumers not to feel rushed or forced into an agreement they aren’t comfortable with.